

Integrating accounting software can transform how businesses handle financial data – reducing manual work, minimizing errors, and improving overall efficiency. Yet, 33% of small-business owners still rely on outdated manual processes, with 44% hesitant to switch due to familiarity with old methods. Done right, integration can reduce month-end close times from 15 days to 5 and cut invoice processing costs by 30%.
Here’s a quick summary of what successful integration involves:
- Preparation: Assess current workflows, identify needs, and ensure compatibility between systems.
- Data Migration: Backup, clean, and map data properly to avoid errors during migration.
- Implementation: Assemble a cross-functional team led by strategic financial leadership, prioritize key integrations, and automate repetitive tasks.
- Testing: Conduct thorough testing with sample and real data to ensure accuracy before going live.
- Post-Go-Live: Monitor transactions, train staff, and document processes for continuous improvement.
The process requires careful planning and regular maintenance. Key metrics like faster month-end closes, fewer manual adjustments, and improved reporting accuracy signal success. With the right approach, businesses can scale efficiently while maintaining accurate, real-time financial insights.
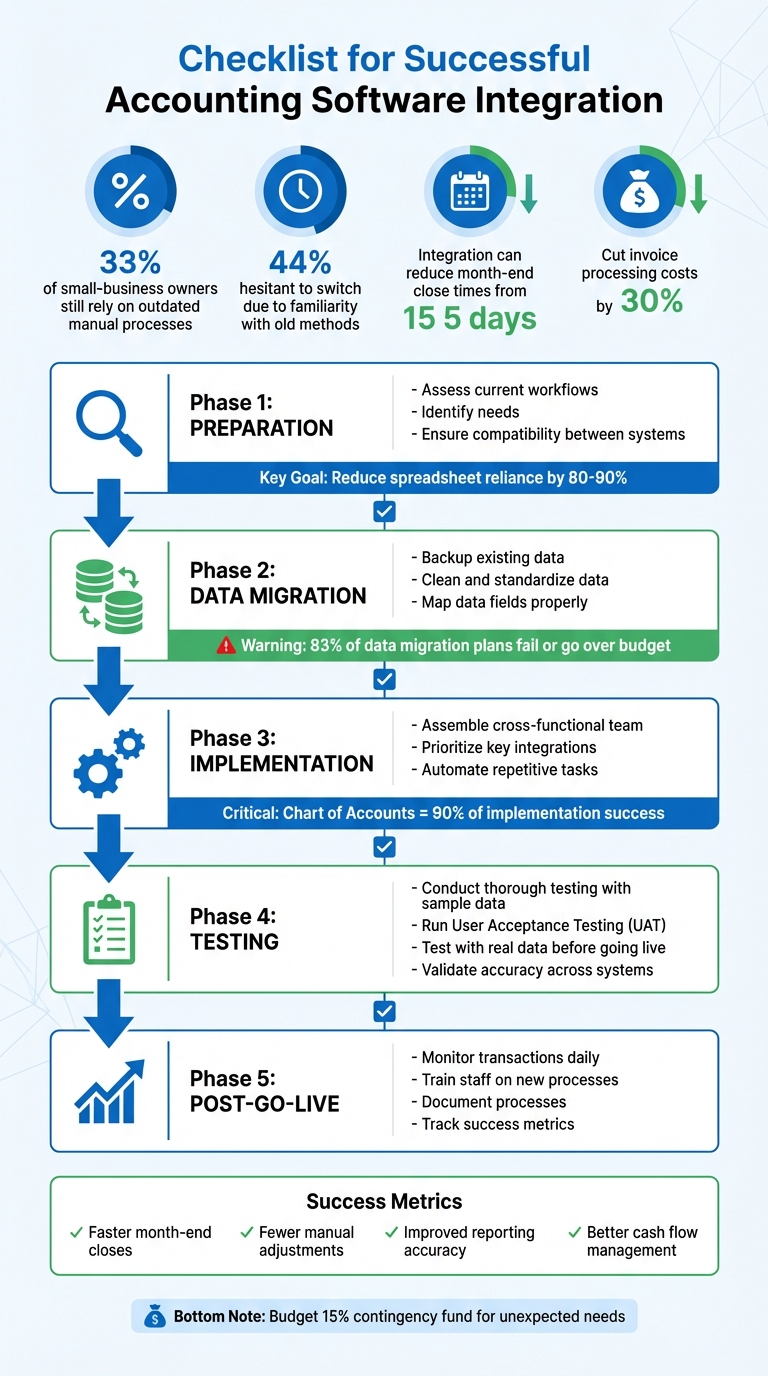
5-Phase Accounting Software Integration Checklist
Integration Best Practices CRM and Accounting/ERP
sbb-itb-85dd802
Preparation Phase Checklist
Start by outlining your current systems and the outcomes you want to achieve. This phase is critical in ensuring your integration goes smoothly, avoiding unexpected delays and costs.
Assess Business Needs and Current Workflows
Take a close look at your current processes. Pinpoint the tasks that consume the most time, especially manual ones. For instance, if your accountants are manually entering invoices or reconciling data using complex spreadsheets, your integration should aim to reduce spreadsheet reliance by 80% to 90% throughout your accounting workflows.
Don’t limit your discussions to just the finance team. Speak with other departments, like sales and operations, to uncover additional needs. For example, sales might require quicker access to customer payment histories, while operations could be struggling with outdated inventory tracking. These conversations can uncover critical requirements you might otherwise miss. Once you gather this input, categorize it into "needs" (like GAAP compliance or multi-entity consolidation) and "wants" (such as strategic financial forecasting). This approach ensures your budget focuses on essentials rather than unnecessary extras.
Finally, evaluate your current systems to confirm they’re technically compatible with the new integration.
Evaluate Software Tools and Compatibility
List every system that interacts with financial data – CRM platforms, payroll tools, e-commerce systems, and banking feeds. Then, determine the level of integration each one needs. For example, does your inventory system require real-time API synchronization to keep stock levels updated instantly? Or would a nightly batch process suffice for tasks like expense reporting?
If you’re using cloud-based software, ensure your hardware meets or exceeds the minimum requirements, such as 8 GB RAM and i5/i7 processors. When exploring software options, request demos that simulate your specific business scenarios. For example, if your company has complex revenue recognition rules or handles international tax calculations, make sure the software can manage those challenges effectively.
Define Integration Goals and Success Metrics
Set clear, measurable goals to track your progress. Examples include reducing month-end close time from 15 days to 5, cutting invoice processing costs by 30%, or improving GAAP reporting accuracy by 25%. These metrics give you a solid benchmark to evaluate the success of your integration.
"Getting your Chart of Accounts (COA) and financial dimensions correct is 90% of implementation success and can drive real business benefits through performance insights." – AAFCPAs
Develop a project charter that outlines the scope, timeline, and budget, along with a 15% contingency fund. This document serves as your guide, helping you stay on track when vendors propose additional features or team members request changes. It’s your safeguard against scope creep, which can derail both your timeline and budget.
Data Migration Best Practices
Moving financial data from one system to another can be a tricky process, often becoming the biggest challenge in integration projects. In fact, 83% of data migration plans fail or go over budget due to poor planning or insufficient expertise. The silver lining? Most of these issues can be avoided by taking a structured approach that includes backing up, cleaning, mapping, and testing your data before the final migration.
Backup and Clean Existing Data
Start by creating a full backup of your financial system, and run a test restore to ensure it works. This backup acts as your safety net. Next, generate a trial balance or balance sheet from your current system. This report will serve as your benchmark to confirm that every dollar migrates correctly.
Cleaning your data is equally critical. Conduct a thorough audit to remove duplicates, fill in missing fields, and eliminate outdated records. For instance, you might find "ABC Supplies Inc." and "ABC Supplies Incorporated" listed as separate vendors when they’re actually the same entity. Extract all master data – including inactive vendors, customers, and items – and create a "Scrub List" for de-duplication. This step is crucial because historical transactions referencing inactive records can cause migration failures.
"Data cleanup is not a cosmetic exercise. It is risk management." – Uncanny CS
Next, standardize your data formats. Normalize dates, currencies, naming conventions, and units of measure to avoid import errors. Also, fill in any mandatory fields required by your new system that might be missing in the old one. To ensure accuracy, establish a data freeze window, a designated period during which no new data can be entered into the old system, so your migrated balances align with your final reports. Assign data owners, such as a Finance lead for your Chart of Accounts, to oversee changes and resolve conflicts during this process.
Once your data is clean and standardized, you’re ready to map and reorganize it for the new system.
Map and Reorganize Data Fields
Develop a detailed mapping specification that outlines every source field, its target field in the new system, the transformation logic, and any validation rules. Extract raw transaction data to ensure all historical elements are accounted for, as active lists often exclude deactivated entities that still appear in your transaction history.
Define clear transformation rules for tasks like merging address lines, splitting data, or adjusting formats for dates and currencies. Use "dimensions" (tags for departments, projects, or locations) to categorize data instead of overloading your Chart of Accounts. For outdated vendors or items, map them to a "historical" dimension to retain context without cluttering active records.
"Fixing data problems in your new system costs 10 times more than addressing them upfront." – Concentrus
Address issues like duplicates, missing tax IDs, or invalid email formats in your legacy system before migration. Fixing these problems later can be far more expensive and disruptive.
With your data fields mapped and organized, it’s time to validate the process through sample data migration.
Test Migration with Sample Data
Avoid running your first full migration on go-live day. Instead, test with a subset of data, such as one customer segment or product category, in a sandbox environment. Use a specific legacy report as your validation standard to reconcile post-migration data.
Compare reports from both systems to ensure record counts, balances, quantities, and totals match perfectly. Run full business cycles – like creating purchase orders, generating invoices, and processing payroll – to confirm that data, configurations, and workflows function seamlessly. Document every issue and its resolution to avoid surprises during the full migration.
"UAT [User Acceptance Testing] should be about business confidence, not data firefighting." – Uncanny CS
Involve business owners from finance and operations in the validation process. Their understanding of the data’s context often surpasses that of IT teams. If possible, test with production-level data volumes to uncover performance issues that small samples might miss. Ensure that migrated records maintain their integrity, such as historical customer orders correctly linking to their corresponding customer master records.
Implementation and Configuration
Once your data is prepped and tested, it’s time to move into the technical setup and workflow configuration. This is where your accounting software transitions from a blank slate into a fully operational system tailored to your business needs. The key to success here lies in assembling the right team, focusing on essential integrations, and automating repetitive tasks.
Assemble a Cross-Functional Team
"Accounting software implementation is a team sport" – The CFO Club
Start by appointing an Executive Sponsor – typically your CFO or COO – to secure resources and provide overall direction. A Project Manager should handle the day-to-day execution. Then, bring in functional experts from different departments and assign "Super Users" to lead peer training efforts.
Your Accounting Team Lead plays a critical role in bridging the gap between the software’s technical capabilities and your accounting needs. This person ensures the Chart of Accounts is structured correctly – a factor that influences about 90% of implementation success. IT specialists are also vital for managing infrastructure, security, and technical integrations.
Involve representatives from HR, Payroll, Sales, and Operations to ensure the software supports workflows specific to each department, such as order-to-cash or expense management. "Super Users" or "System Champions" from each team can help train colleagues and provide first-level support once the system is live.
"A clear implementation structure with defined roles, responsibilities, and decision-making authority helps prevent ambiguity and delays when it’s time to go live." – NetSuite
Keep the decision-making team compact to avoid unnecessary delays, but engage stakeholders early to address unique needs and ease the transition to the new system.
Prioritize Key Integrations
Instead of attempting to connect all systems at once, use a phased approach. Start with the essentials, like the General Ledger and reporting tools, before moving on to specialized modules like Accounts Receivable, Payroll, or Inventory. This allows users to gain confidence with the core system before tackling more complex workflows.
Focus on one high-value process at a time. For instance, you might begin by automating the flow of approved invoices to the ledger before introducing features like multi-currency transactions or partial payments. Industry-specific tax and accounting needs should guide your priorities: construction companies might prioritize job costing, while agencies may need time-based billing.
Decide between real-time and batch processing based on the type of data. Time-sensitive information, like inventory levels or e-commerce transactions, may require real-time API integrations. In contrast, systems like HRIS or payroll can sync on a batch schedule. Clearly define the "source of truth" for each type of data. For example, contracts and billing schedules might live in your CRM, while tax filings and account balances stay within the accounting platform.
"Bad data is the enemy." – Jeff Heybruck, CEO, Lucrum Consulting
Before connecting any systems, perform a mini audit of your CRM, inventory management, or other platforms to clean up data. This prevents the "garbage in, garbage out" scenario. Plan your final system cutover to align with a month-end or year-end close for clean, reconciled opening balances.
Set Up Automation and Custom Workflows
Take a close look at your existing workflows and redesign them with automation in mind. Don’t just digitize manual processes – leverage the logic and automation features your software provides.
Roll out automation gradually to allow time for troubleshooting and adjustment. Start with recurring tasks like invoice approvals, expense categorization, and bank reconciliation. Use automation rules and custom fields to route transactions based on specific criteria.
Collaborate with your IT team to implement safeguards like idempotency keys for all write operations. This prevents duplicate payments or journal entries if a network issue triggers transaction retries. Carefully review integration permissions to avoid exposing sensitive financial data to unauthorized users. Also, confirm whether integrations are one-way or two-way, as some off-the-shelf connections only push data into the accounting software without updating the source system.
"Accounting integrations fail not because accounting is complex, but because teams underestimate domain-specific workflows, platform differences, and long-term maintenance costs." – Kateryna Poryvay, Apideck
During the go-live phase, set up a temporary "Command Center" staffed with IT, accounting, and vendor representatives to monitor system performance and integration syncs in real time. With automation and workflows in place, your system will be ready for thorough testing and a seamless transition to full operation.
Testing and Go-Live Checklist
Before making your integration live, ensure every component functions as expected in real-world conditions. This step is crucial for avoiding costly mistakes and ensuring a smooth transition.
Conduct End-to-End Testing
Start with unit tests to validate individual tasks, then move on to System Integration Testing (SIT) to check data flow between systems like ERP, CRM, and payroll. Finally, test complete processes such as Order-to-Cash or Procure-to-Pay to confirm everything works seamlessly.
"Technical testing ensures data moves, but accounting testing ensures it moves correctly." – Andrew Schwartz Crane, CMA, SoundPost AI
Test both routine and complex scenarios, including refunds, chargebacks, and multi-entity transactions, to ensure the system can handle a variety of situations. For accuracy, compare trial balance reports from your old system with those from the new one – totals should match exactly. Also, simulate peak transaction volumes and external system downtimes to see how the integration performs under pressure.
User Acceptance Testing (UAT) is another essential step. Use actual migrated data instead of sample data to make sure the system works as intended. Running your old and new systems in parallel for one or two billing cycles can provide additional assurance before fully transitioning to the new platform.
Once testing confirms readiness, the focus shifts to preparing your team.
Train Staff on New Processes
After thorough testing, it’s time to equip your team with the knowledge they need to operate the new system effectively. Tailor training sessions to specific roles – accounts payable staff will need different guidance than treasury teams. Offer a mix of live training, on-demand videos, and in-system walkthroughs to cater to different learning preferences.
"Educate end-users too early and they may forget everything they learned about the new system. Instead, find a sweet spot and train them just in time for the software implementation." – Clea Badion, Nelson Connects
Announce training schedules well in advance to ensure everyone is prepared. Focus on real-world scenarios and edge cases during these sessions, and create Standard Operating Procedures (SOPs) that employees can reference post-launch. Additionally, provide advanced training for "Super Users" who can act as internal support for their colleagues.
Monitor Initial Transactions Post-Go-Live
During the first month after going live, closely monitor transactions to quickly address any issues. Set up a dedicated command center and hold daily stand-ups to resolve problems as they arise.
Use real-time dashboards to track transaction statuses and flag incomplete records. Exception queues can help finance staff review and correct flagged items before they reach the General Ledger. Keep an eye on key metrics like Days Sales Outstanding (DSO), Days Payable Outstanding (DPO), and reconciliation exceptions to identify bottlenecks early.
"Integrations are not ‘set and forget.’ Even when they function reliably, finance leaders should view them as living processes that can be refined over time." – Andrew Schwartz Crane, CMA, SoundPost Bridge
Your first month-end close is a critical milestone. Compare results from the new system with those from your legacy system to evaluate both accuracy and speed. Log any issues – whether access problems, reporting errors, or training gaps – in a ticketing system. This will help you determine if further adjustments or additional training are required.
Maintenance and Optimization
Keeping your integration running smoothly requires regular upkeep, just like the careful planning and testing that went into its initial setup. Accounting systems are constantly adapting to new products, tax regulations, and API changes. Without proper maintenance, performance can take a hit.
Schedule Regular Performance Reviews
Set up a consistent schedule for performance reviews to address potential issues early. Weekly check-ins should focus on operational health: examine metrics like Days Sales Outstanding (DSO) and Days Payable Outstanding (DPO), review exception queues for stuck transactions, and monitor sync alerts. Monthly reviews should coincide with your close process – conduct full reconciliations between your general ledger and sub-ledgers (like deferred revenue or cash deposits) to ensure everything aligns.
Quarterly leadership meetings are a great opportunity to align your integration plans with your business goals. Use these sessions to analyze audit logs, gather feedback from staff about any pain points, and update data mappings to reflect changes like new products or pricing structures. Don’t forget to check for API updates from your software providers, especially regarding deprecation cycles and changes to authentication protocols like OAuth scopes or token lifetimes. Annual reviews should include comprehensive compliance checks (e.g., SOX, GDPR), disaster recovery testing, and scalability assessments to handle growing transaction volumes.
Automated alerts can catch issues like failed postings, missing attributes, or unusual transaction patterns. Keep an eye on key performance indicators (KPIs) such as the frequency of manual journal entries and the time it takes to close the books each month. These reviews will help you build a foundation for continuous improvement and maintain strong security protocols.
Document Processes and Updates
Thorough documentation is essential for the long-term reliability of your integrations. Clearly outline your integration logic and configuration decisions. Use a spreadsheet to map how data fields link between systems, including details like transformation rules, rounding methods, and validation logic. Specify which system owns each data attribute – for instance, QuickBooks might handle invoice totals while your CRM tracks deal stages. This clarity minimizes conflicts during data synchronization.
"Documentation should be updated with each approved change, and mappings or posting rules should be versioned so that history is preserved." – Andrew Schwartz Crane, CMA, SoundPost
Develop troubleshooting guides and log issues in a ticketing system to create a searchable database for quick problem-solving. Maintain a backlog for change requests and tackle them during planned update sprints instead of making ad-hoc changes that could disrupt the system.
Always update your documentation after any approved changes. Version your mappings and posting rules to maintain a clear record of historical data flows, which is particularly useful during audits. Standard operating procedures can also double as training materials for new team members, ensuring everyone stays on the same page.
Ensure Compliance and Security
Strong security measures and compliance practices are critical to keeping your integration safe and reliable. Regulations like the FTC Safeguards Rule mandate multi-factor authentication (MFA) across all systems, including tax software and client portals. Non-compliance can result in penalties of up to $43,000 per violation per day. Enforce role-based access controls to ensure employees only access the data they need for their roles. Since 81% of data breaches in the financial sector stem from compromised credentials, MFA is a must.
Conduct annual security audits, including internal reviews, penetration testing, and third-party evaluations to spot vulnerabilities. Regularly test your backup restoration process and establish clear Recovery Time Objectives (RTOs). Verify backups frequently to ensure they work as intended. Use electronic audit trails to track all user actions – whether they’re modifying, deleting, or editing documents – so you have transparent records for compliance purposes.
Automate document retention based on federal and state requirements, and schedule regular security training sessions to prepare your team for phishing attempts, which spike by 350% during tax season. When rolling out integration updates, plan your "go-live" date to coincide with a period close, ensuring a clean transition between old and new data sets.
Conclusion
Successfully integrating accounting software takes more than just flipping a switch – it requires thoughtful planning, precise execution, and ongoing adjustments. One of the most critical steps? Getting your Chart of Accounts set up correctly. This foundational element ensures a smoother transition and sets the stage for long-term success.
"Implementing accounting software isn’t a one-and-done project; it’s an ongoing journey of optimization, insight, and growth." – The CFO Club
To ensure success, you need both a sound strategy and the right tools. Running your old and new systems side-by-side for at least one full accounting cycle is a smart move. It allows you to verify data accuracy before decommissioning your legacy system. Timing your go-live during slower business periods can also help reduce disruptions and make it easier for your team to adapt.
Once the software is live, the work doesn’t stop. Regular reviews – at 30, 60, and 90 days – can help you identify any issues, collect feedback, and uncover features you might not be fully utilizing. Assigning an internal "power user" or champion ensures that your team has someone to turn to for guidance and support. And don’t forget to budget for the unexpected – a contingency fund of about 15% of the total implementation cost can be a lifesaver for unplanned needs.
As you continue optimizing your system, keep an eye on measurable results. Faster month-end closes, fewer manual journal entries, improved reporting accuracy, and better cash flow through automated reminders are all signs that your integration is on track. When your general ledger aligns seamlessly with sub-ledgers without manual adjustments, you know your system is performing as it should.
The businesses that thrive are those that treat their accounting software as a dynamic tool – ready to adapt to new regulations, API changes, and growth opportunities – rather than a static, one-time solution.
For personalized advice and expert support at every step of your accounting software journey, contact our team at TC Advisors.
FAQs
How long does an accounting software integration usually take?
Integrating accounting software typically takes anywhere from 6 to 16 weeks. The exact timeline can vary based on several factors, such as the complexity of the system, the number of entities involved, the specific modules required, the volume of data being transferred, and any custom features needed. Careful planning and preparation play a big role in keeping the process as smooth as possible.
What data should we migrate, and what can we leave behind?
When moving accounting data, concentrate on key details such as current balances, past transactions, customer and vendor records, and account structures. Skip transferring outdated, irrelevant, or duplicate data. To streamline the process, consider migrating summary balances rather than the entire history of transactions. Leave behind old or redundant records that no longer affect current reporting or compliance. Focus on active, relevant data to ensure smooth and accurate financial management.
How can we avoid duplicate or missing transactions after go-live?
To prevent duplicate or missing transactions after go-live, it’s crucial to put in place robust workflow controls and validation measures. Incorporate unique identifiers, such as idempotency keys, to spot duplicates quickly. A staging area can help ensure data is ingested consistently and without errors.
Establish an exception review process with detailed audit trails to tackle any discrepancies effectively. Additionally, ongoing reconciliation and monitoring play a key role in maintaining transaction accuracy and uncovering patterns that might highlight recurring issues, paving the way for continuous refinement.


